menu 
According to the Vietnam Association of Seafood Exporters and Producers (VASEP), seafood exports remained above US$1.1 billion in September, with a higher growth rate than in August. However, export value edged down slightly from the previous month. The figures indicate that trading activity remained strong toward the end of the year, although growth momentum varied considerably across product categories and markets.
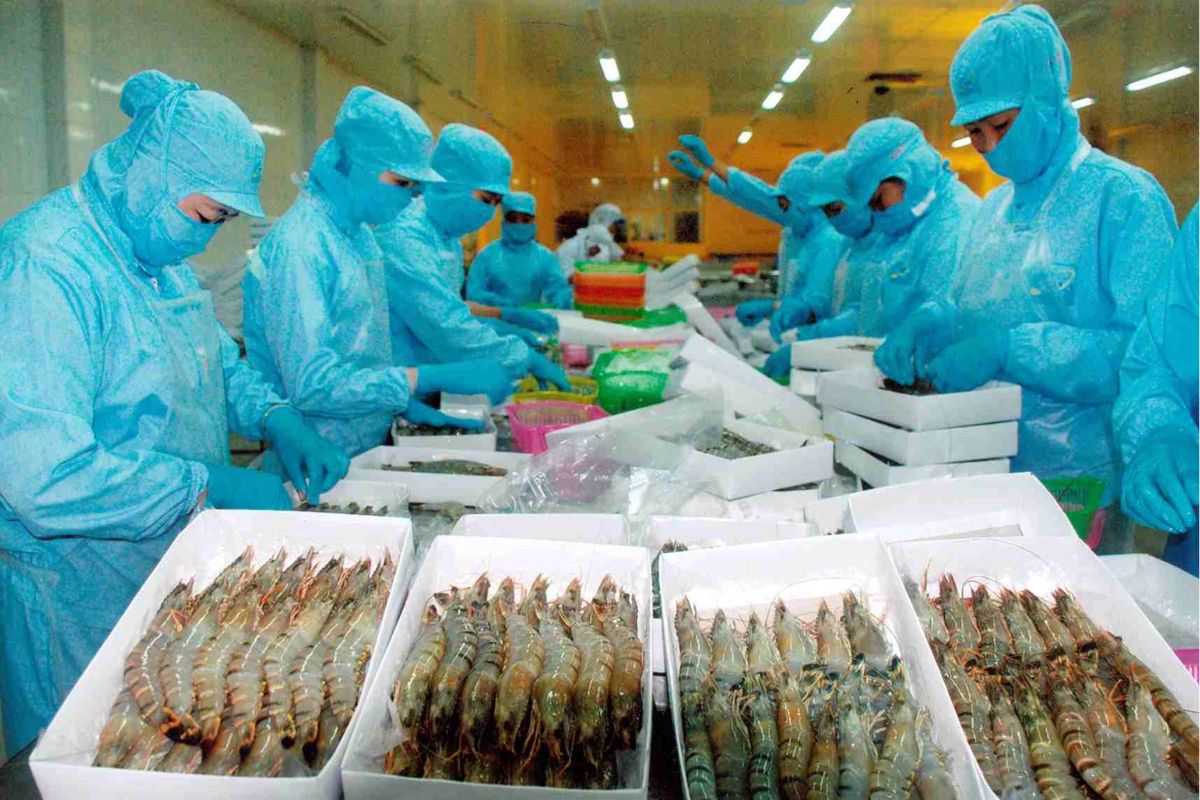
Shrimp growth slows, while pangasius and other seafood maintain momentum
Shrimp remained Vietnam’s leading seafood export product, but its growth momentum showed signs of slowing. September shrimp exports were estimated at US$467 million, up 3.9%. For the first nine months of 2026, shrimp exports reached US$3.75 billion, an 11% increase year on year.
Accounting for around 41% of Vietnam’s total seafood export turnover, shrimp has a significant influence on the overall performance of the sector. The modest growth recorded in September indicates that further expansion of orders is facing pressure from supply competition and the purchasing capacity of major markets.
Data presented at the Global Shrimp Forum in September showed that China’s shrimp imports were growing faster than consumption, while EU imports of raw shrimp declined and varied across regions. In the United States, frozen shrimp sales volumes fell in August despite higher revenues. These developments suggest that Vietnam’s shrimp export growth does not yet reflect a broad-based recovery in global shrimp demand. Meanwhile, pangasius performed more positively. September exports reached approximately US$214 million, up 18.6%, bringing the nine-month total to US$1.74 billion, up 10.7% year on year.
According to VASEP, tighter supplies of certain wild-caught whitefish are creating additional opportunities for Vietnamese pangasius. In Japan, Kyokuyo’s continued introduction of pangasius through professional distribution channels is a notable development, although Japan remains a relatively small market for the product. Competitive pricing and stable supply are helping pangasius attract greater interest in several markets. For tuna, September exports reached approximately US$82 million, up 13.1%. Cumulative exports for the first nine months stood at US$716 million, an increase of 3.5% compared with the same period last year.
VASEP noted that monthly growth was significantly higher than the cumulative growth rate. However, the outlook remains dependent on import conditions in the United States and catch documentation requirements in the EU. Improving sales of canned tuna in the US is supporting demand, but this has yet to translate immediately into a corresponding increase in orders from Vietnam.
Other seafood categories also made significant contributions to overall growth. During the first nine months of 2026, fish exports reached US$1.741 billion, up 12.2%; squid and octopus reached US$606 million, up 15.4%; while crab, swimming crab and other crustaceans reached US$354 million, up 31.6%.
For mollusks, nine-month exports totaled US$231 million, up 25.2%. However, exports in September alone declined by 3.5%, indicating that the category’s growth momentum may be beginning to slow.
China - Hongkong and ASEAN surge as US, EU and Japan move in the opposite direction
By export market, China–Hong Kong remained the standout performer for Vietnam’s seafood industry. September exports reached approximately US$315 million, up 39.9%. For the first nine months, exports to the market reached US$2.3 billion, up 33% year on year and accounting for roughly one-quarter of Vietnam’s total seafood exports.
Based on available data, the additional export value generated by China–Hong Kong accounted for approximately 62% of Vietnam’s year-on-year increase in seafood export turnover. However, purchasing power in the market should also be assessed in the context of domestic supply and competition from imported products.
China’s resumption of fishing activities in the Yellow Sea–Bohai Sea region from early September has added to domestic seafood supply. At the same time, the restoration of export rights for several shrimp facilities in Ecuador has provided buyers with additional sourcing options. As a result, despite strong growth in China–Hong Kong, Vietnamese exporters may face greater price competition.
The ASEAN market also recorded strong growth. Seafood exports to the region reached nearly US$84 million in September, up 45.4%, while cumulative exports for the first nine months reached US$620 million, up 21% year on year. South Korea also maintained positive momentum, with exports rising 16.4% in September. Nine-month export turnover reached US$652 million, up 6.1% year on year. Together with other markets, which recorded 17.3% growth over the first nine months, these destinations are helping sustain Vietnam’s overall seafood export growth as traditional markets face increasing challenges.
In contrast, exports to the United States fell 3.4% in September to US$176 million. Cumulative exports for the first nine months reached US$1.43 billion, representing only a 0.9% increase from the same period last year. Additional tariff costs, along with requirements related to the Marine Mammal Protection Act (MMPA) and Certificates of Analysis (COA), continue to affect trade. Retail demand has also been mixed: canned seafood sales increased in volume, while revenues from fresh and frozen seafood rose mainly due to higher prices. In the EU, seafood exports declined 12.8% in September to US$93 million. Cumulative exports for the first nine months reached US$843 million, down 3%.
Similarly, exports to Japan fell 13.7% in September, bringing cumulative growth for the first nine months down to just 0.8%, with export turnover reaching US$1.25 billion.
Seafood exports expected to slow in Q4 2026 as many orders were delivered early
Following a period of acceleration in the third quarter of 2026, Vietnam’s seafood exports are expected to lose momentum in Q4. According to VASEP, many orders intended to meet year-end consumer demand were imported and delivered earlier than usual, making it more difficult for additional purchasing demand to remain at the high levels seen in recent months. With a nine-month export turnover estimated at US$9.103 billion, VASEP forecasts that Vietnam’s total seafood exports could reach approximately US$12 billion in 2026.
However, the outlook for the remaining months remains under pressure from both supply and demand. Shrimp, pangasius and tilapia are all facing raw material supply constraints, while market competition is intensifying and buyers are becoming more cautious about prices. For wild-caught seafood, the ability to expand export volumes is also constrained by the availability of suitable raw materials and increasingly stringent requirements concerning traceability and origin. Against this backdrop, although demand remains relatively strong in some markets, exporters’ ability to fulfill orders could become a limiting factor for growth toward the end of the year. China–Hong Kong and ASEAN are expected to continue supporting Vietnam’s seafood exports in Q4 2026. However, growth in these markets is unlikely to fully offset the slowdown in the United States, the EU and Japan.
As a result, Q4 2026 export performance is likely to be lower than in Q3. Vietnam’s full-year seafood exports are still expected to exceed the previous year’s level, but the growth rate is likely to narrow significantly compared with the double-digit growth recorded during the first nine months of the year.